Bear of the Day: Amrize (AMRZ)
Amrize (AMRZ) shares have been under considerable pressure as investors reassess the building-materials company's earnings trajectory, margins, and execution.
Amrize AMRZ) shares have been under considerable pressure as investors reassess the North American-focused building-materials company's earnings trajectory, margins, and execution.
Trading near a 52-week low of $36 a share, AMRZ is down 30% year to date after falling nearly 15% over the last month.
Adding to the bearish sentiment, Amrize was recently added to the Zacks Rank #5 (Strong Sell) list as earnings estimates have moved sharply lower.
That said, here are three key reasons investors may want to remain cautious on AMRZ.
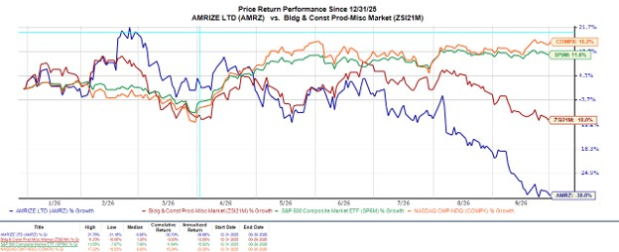
Image Source: Zacks Investment Research
1. Consecutive Earnings Misses & Weaker Profitability
Amrize has missed earnings expectations in each of the first two quarters of 2026.
Q1 adjusted earnings came in at a loss of $0.16 per share, compared with the Zacks EPS Consensus of -$0.14. Furthermore, Q2 adjusted EPS of $0.88 also missed the consensus estimate of $0.92.
More concerning has been profitability. Despite Q2 revenue rising 8%, Amrize's adjusted EBITDA margin slipped to 28.2% from 29%. Building Materials margins contracted 100 basis points, while Building Envelope margins fell 350 basis points. The latter segment includes roofing, insulation, and wall products designed to protect the exterior of buildings.
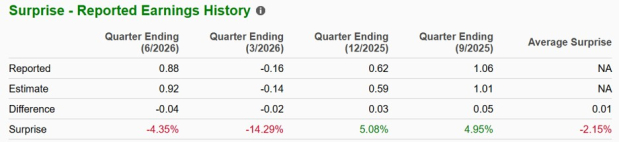
Image Source: Zacks Investment Research
2. Lower Guidance & Falling Earnings Estimates
Following Q2 results, Amrize revised its 2026 adjusted EBITDA outlook to $3.1-$3.2 billion from $3.25-$3.34 billion, citing oil-driven inflation in freight, diesel, and raw-material costs. The company expects those higher costs to remain a headwind to full-year earnings.
That weakening outlook has filtered directly into analyst earnings estimates, as FY26 and FY27 EPS projections have continued to decline in the last month and are now down over 7% in the last 60 days. Furthermore, current quarter and next quarter EPS revisions have fallen more than 13% and 56% in the last two months, respectively.
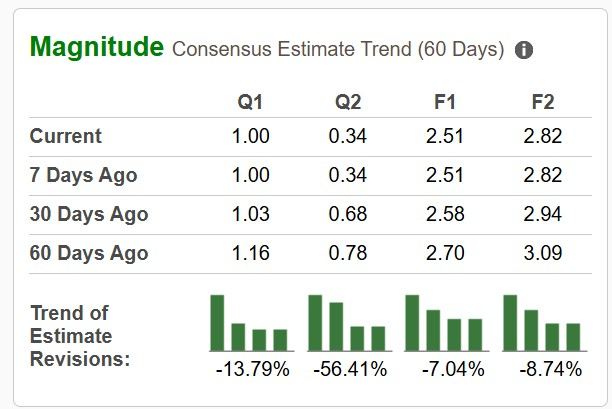
Image Source: Zacks Investment Research
3. Tariffs Add Another Risk for Amrize
Amrize's significant Canadian operations leave the company exposed to the broader fallout from U.S.-Canada trade tensions. Bank of America BAC) specifically cited tariffs as a risk to Canadian demand when lowering its outlook for the company.
To that point, the U.S. imposed 50% Section 338 tariffs on a wide range of Canadian goods this summer without a United States-Mexico-Canada Agreement (USMCA) exemption. Portland cement was initially affected, creating added uncertainty for Amrize's cross-border operations, although non-white Portland cement was subsequently removed from the tariff list effective Sept. 15.
Still, weaker Canadian demand and broader trade uncertainty represent additional concerns for a company already battling elevated costs and margin pressure.
Bottom Line
Amrize still has considerable exposure to long-term infrastructure and construction spending across North America, but its near-term earnings picture has deteriorated.
Two straight earnings misses, lower EBITDA expectations, margin pressure, analyst downgrades, and tariff-related uncertainty have contributed to AMRZ's steep decline. Recent leadership changes, including a new president for the Building Envelope segment, add another layer of execution uncertainty during an already challenging period.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amrize Ltd (AMRZ): Free Stock Analysis Report
Bank of America Corporation (BAC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).